
Most people comparing the old tax regime vs new tax regime are really asking one question: how much in deductions do I need before the old regime saves me money? The answer depends on your salary, and it is smaller than many people expect.
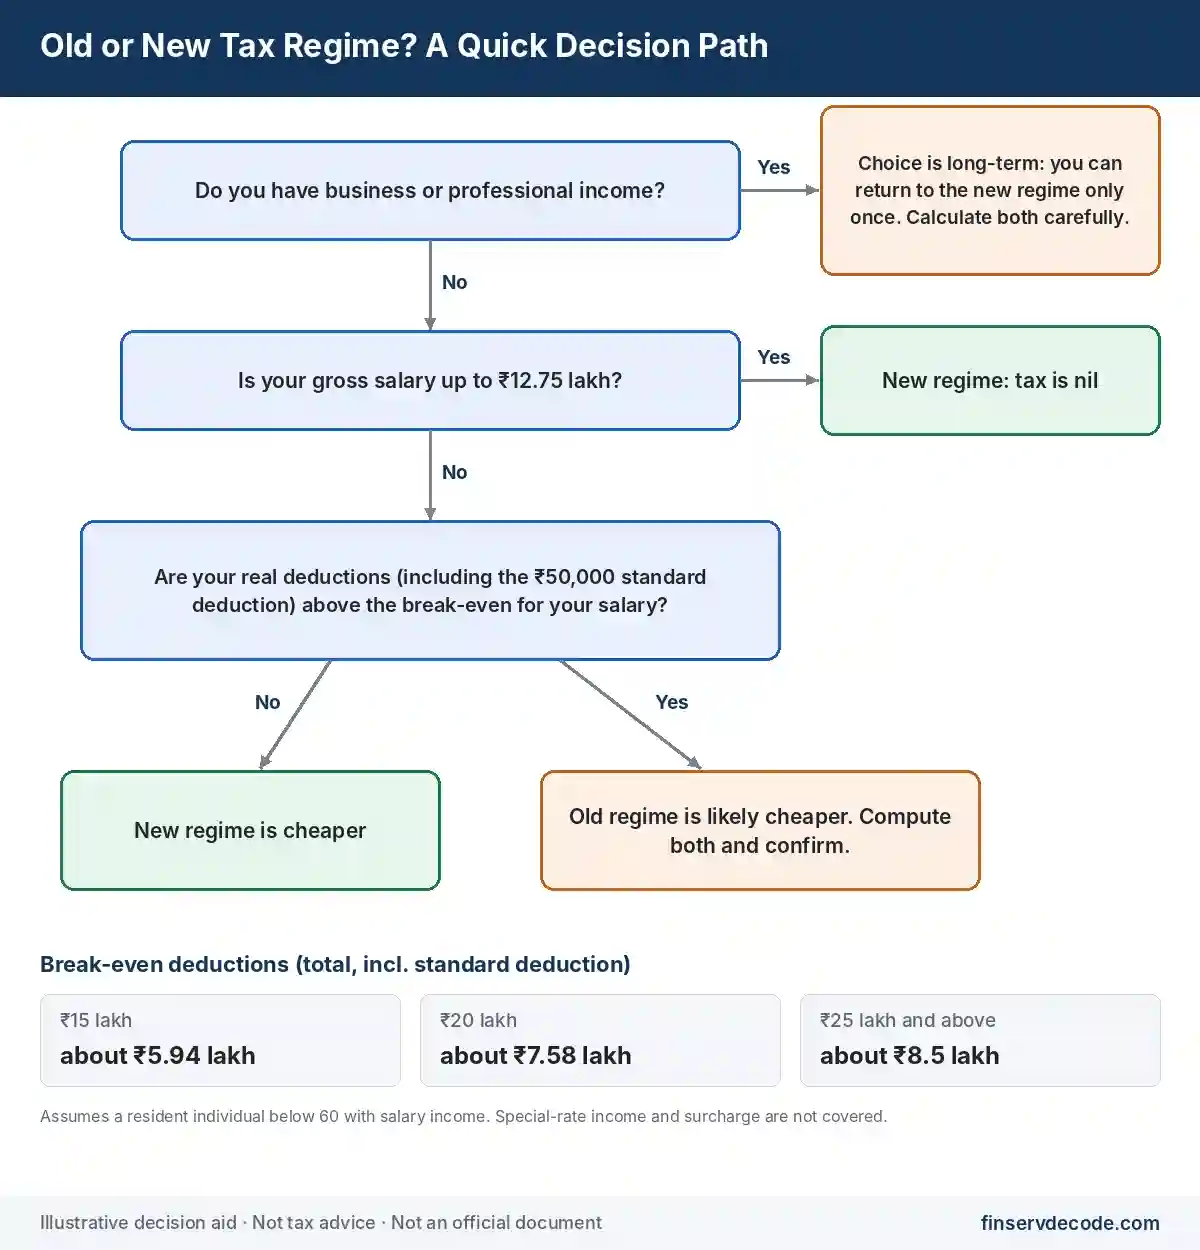
For a resident individual with only salary income, the old regime starts to win once your total deductions cross about ₹5.94 lakh at a ₹15 lakh salary, about ₹7.58 lakh at ₹20 lakh, and about ₹8.5 lakh at ₹25 lakh or more. These totals include the ₹50,000 standard deduction. If your real deductions are below that figure, the new regime costs you less. Up to a salary of ₹12.75 lakh, the new regime makes your tax nil, which is very hard for the old regime to match.
The new regime is now the default. It has lower slab rates and a ₹75,000 standard deduction, but it drops most deductions, including HRA, 80C, 80D, and home loan interest on the house you live in. The old regime keeps those deductions but taxes you at higher rates. The slab rates are the same for FY 2025-26 (AY 2026-27) and Tax Year 2026-27, the first year under the Income-tax Act, 2025, so the old vs new tax regime comparison below works for both.
Which Tax Regime Is Better for Your Salary?
This table is the quickest way to decide which tax regime is better for you. For each salary, it shows the tax you pay in the new regime, which does not depend on your investments, and the total deductions you would need in the old regime to pay the same tax. If your deductions are higher than that figure, the old regime wins.
The figures are illustrative. They assume a resident individual below 60 with salary income only, no special-rate income such as capital gains, and no employer NPS contribution. All tax figures include 4% cess.
| Gross Salary | Taxable Income (New Regime) | Tax in New Regime | Total Deductions Needed in Old Regime | Needed Beyond the ₹50,000 Standard Deduction |
|---|---|---|---|---|
| ₹10 lakh | ₹9,25,000 | Nil | ₹5,00,000 | ₹4,50,000 |
| ₹12 lakh | ₹11,25,000 | Nil | ₹7,00,000 | ₹6,50,000 |
| ₹12.75 lakh | ₹12,00,000 | Nil | ₹7,75,000 | ₹7,25,000 |
| ₹15 lakh | ₹14,25,000 | ₹97,500 | About ₹5,93,750 | About ₹5,43,750 |
| ₹18 lakh | ₹17,25,000 | ₹1,50,800 | About ₹6,91,670 | About ₹6,41,670 |
| ₹20 lakh | ₹19,25,000 | ₹1,92,400 | About ₹7,58,330 | About ₹7,08,330 |
| ₹25 lakh | ₹24,25,000 | ₹3,19,800 | About ₹8,50,000 | About ₹8,00,000 |
| ₹30 lakh | ₹29,25,000 | ₹4,75,800 | About ₹8,50,000 | About ₹8,00,000 |
| ₹40 lakh | ₹39,25,000 | ₹7,87,800 | About ₹8,50,000 | About ₹8,00,000 |
| ₹50 lakh | ₹49,25,000 | ₹10,99,800 | About ₹8,50,000 | About ₹8,00,000 |
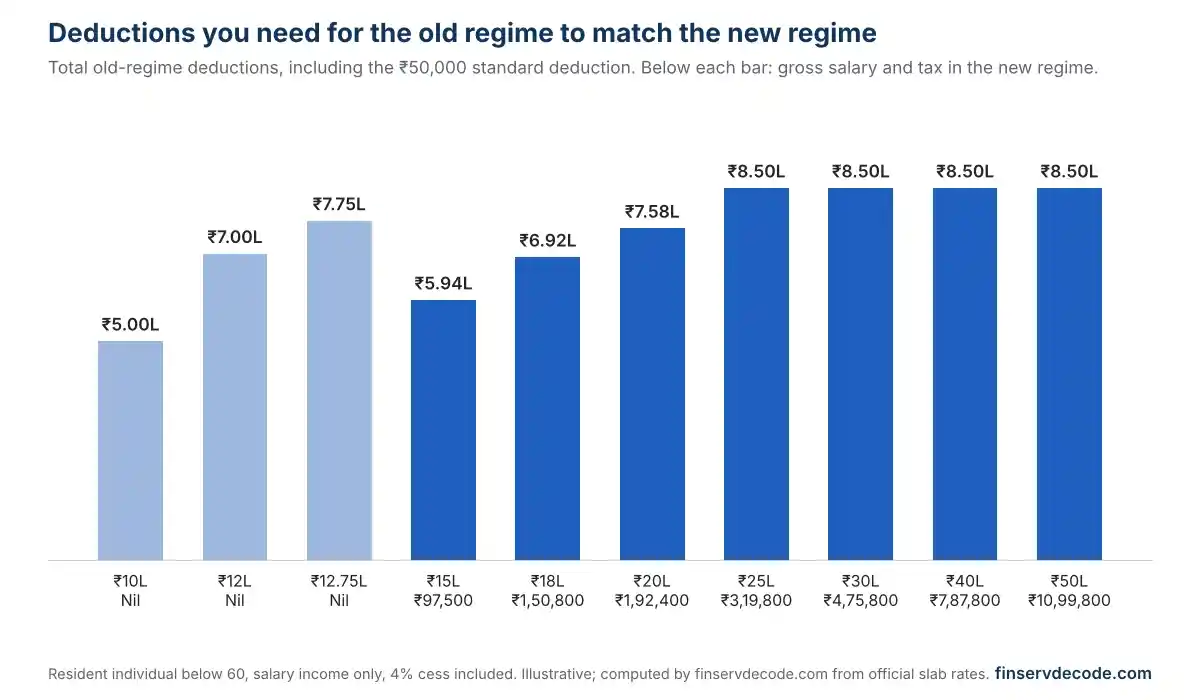
Read the break-even as the total of deductions you already have, not as an investment target. Your standard deduction, HRA exemption, home loan interest, and the premiums you already pay all count towards it.
What the numbers show:
- Up to ₹12.75 lakh, the new regime is very hard to beat. Your tax is already nil, so the old regime would have to bring your taxable income down to ₹5 lakh as well. At a ₹12 lakh salary, that means ₹7 lakh or more of deductions, which few salaried people have.
- Between ₹15 lakh and ₹25 lakh, the break-even climbs from about ₹5.94 lakh to about ₹8.5 lakh. This is the band where HRA in a big city plus a home loan can tip the result, so work out both.
- From about ₹24.75 lakh upward, the break-even stays near ₹8.5 lakh. Once your income is in the 30% slab under both regimes, each extra rupee is taxed at the same rate in both, so the gap stops growing. You need the same ₹8.5 lakh at ₹50 lakh as at ₹30 lakh.
You may notice that the figure dips at ₹15 lakh (₹5.94 lakh) compared with ₹12 lakh (₹7 lakh). That is because the new regime is no longer tax-free at ₹15 lakh, so the old regime only has to beat a positive tax figure, not nil. For a salary between two rows, such as ₹17 lakh, the break-even sits between the two nearest figures. Use it as a first check, then work out the actual tax.
Which tax regime is better for a ₹20 lakh salary?
For a ₹20 lakh salary, the new regime tax is ₹1,92,400. The old regime matches it only when your total deductions reach about ₹7.58 lakh. Here is a realistic case.
A salaried employee in a metro city earns ₹20 lakh a year. Basic salary is ₹8 lakh, HRA received is ₹4 lakh, and the rent paid is ₹30,000 a month (₹3.6 lakh a year). The HRA exemption is the lowest of ₹4 lakh (HRA received), ₹2.8 lakh (rent minus 10% of basic), and ₹4 lakh (50% of basic), so it is ₹2.8 lakh. All figures are assumed for illustration.
| Item | Old Regime | New Regime |
|---|---|---|
| Gross salary | ₹20,00,000 | ₹20,00,000 |
| Standard deduction | ₹50,000 | ₹75,000 |
| Professional tax | ₹2,500 | Not allowed |
| HRA exemption | ₹2,80,000 | Not allowed |
| Section 80C (EPF + PPF) | ₹1,50,000 | Not allowed |
| Section 80D (family health cover) | ₹25,000 | Not allowed |
| Section 80CCD(1B) (own NPS) | ₹50,000 | Not allowed |
| Total deductions | ₹5,57,500 | ₹75,000 |
| Taxable income | ₹14,42,500 | ₹19,25,000 |
| Tax including 4% cess | ₹2,55,060 | ₹1,92,400 |
The new regime is cheaper by ₹62,660, even with HRA and three common deductions. ₹5.58 lakh is still about ₹2 lakh short of the break-even. Closing that gap would need something like interest on a home loan for a house you live in, which this person cannot have on a house they rent.
When the old regime does win
Now take a ₹15 lakh salary with these deductions: HRA exemption of ₹2.4 lakh, 80C of ₹1.5 lakh, 80D of ₹75,000 (₹25,000 for the family plus ₹50,000 for senior citizen parents), 80CCD(1B) of ₹50,000, education loan interest of ₹60,000, professional tax of ₹2,500, and the ₹50,000 standard deduction. The total is ₹6,27,500, which is above the ₹5.94 lakh break-even.
Old regime tax: ₹90,480. New regime tax: ₹97,500. The old regime saves ₹7,020.
That margin is thin. Take away the parents’ health cover or the education loan, and the new regime is cheaper again. The example also assumes every deduction is eligible and backed by records.
Difference Between Old and New Tax Regime
The difference between the old and new tax regime goes well beyond slab rates. This table puts every point that changes your tax bill in one place for an individual below 60.
| Point | Old Tax Regime | New Tax Regime |
|---|---|---|
| Status | Optional. You must choose it | Default under Section 115BAC (Section 202 from Tax Year 2026-27) |
| Basic exemption limit | ₹2.5 lakh (₹3 lakh at 60+, ₹5 lakh at 80+) | ₹4 lakh at every age |
| 30% rate starts above | ₹10 lakh | ₹24 lakh |
| Rebate (Section 87A / Section 156) | Up to ₹12,500 if taxable income is up to ₹5 lakh | Up to ₹60,000 if taxable income is up to ₹12 lakh, plus marginal relief |
| Standard deduction | ₹50,000 | ₹75,000 |
| HRA and LTA exemption | Allowed | Not allowed |
| Section 80C, 80D, 80E, 80G, 80TTA/80TTB | Allowed | Not allowed |
| Home loan interest, self-occupied house | Up to ₹2 lakh | Not allowed |
| Home loan interest, let-out house | Allowed; loss set off against other income up to ₹2 lakh | Allowed against rent; a loss cannot be set off against other income |
| Employer NPS, Section 80CCD(2) | 10% of salary (14% for government employees) | 14% of salary for all employers |
| Highest surcharge (normal income) | 37% (income above ₹5 crore) | 25% |
| Paperwork | Proofs for each claim must be kept (not attached to the ITR) | Very little |
Old vs New Tax Regime Slabs for FY 2025-26 and Tax Year 2026-27
The Finance Bill, 2026 did not change any personal income tax rates. Its Memorandum says the rates for individuals stay the same, with the Section 202 slabs applying from Tax Year 2026-27. So the tables below hold for FY 2025-26 (return filed in 2026) and for Tax Year 2026-27 (income earned from 1 April 2026 to 31 March 2027).
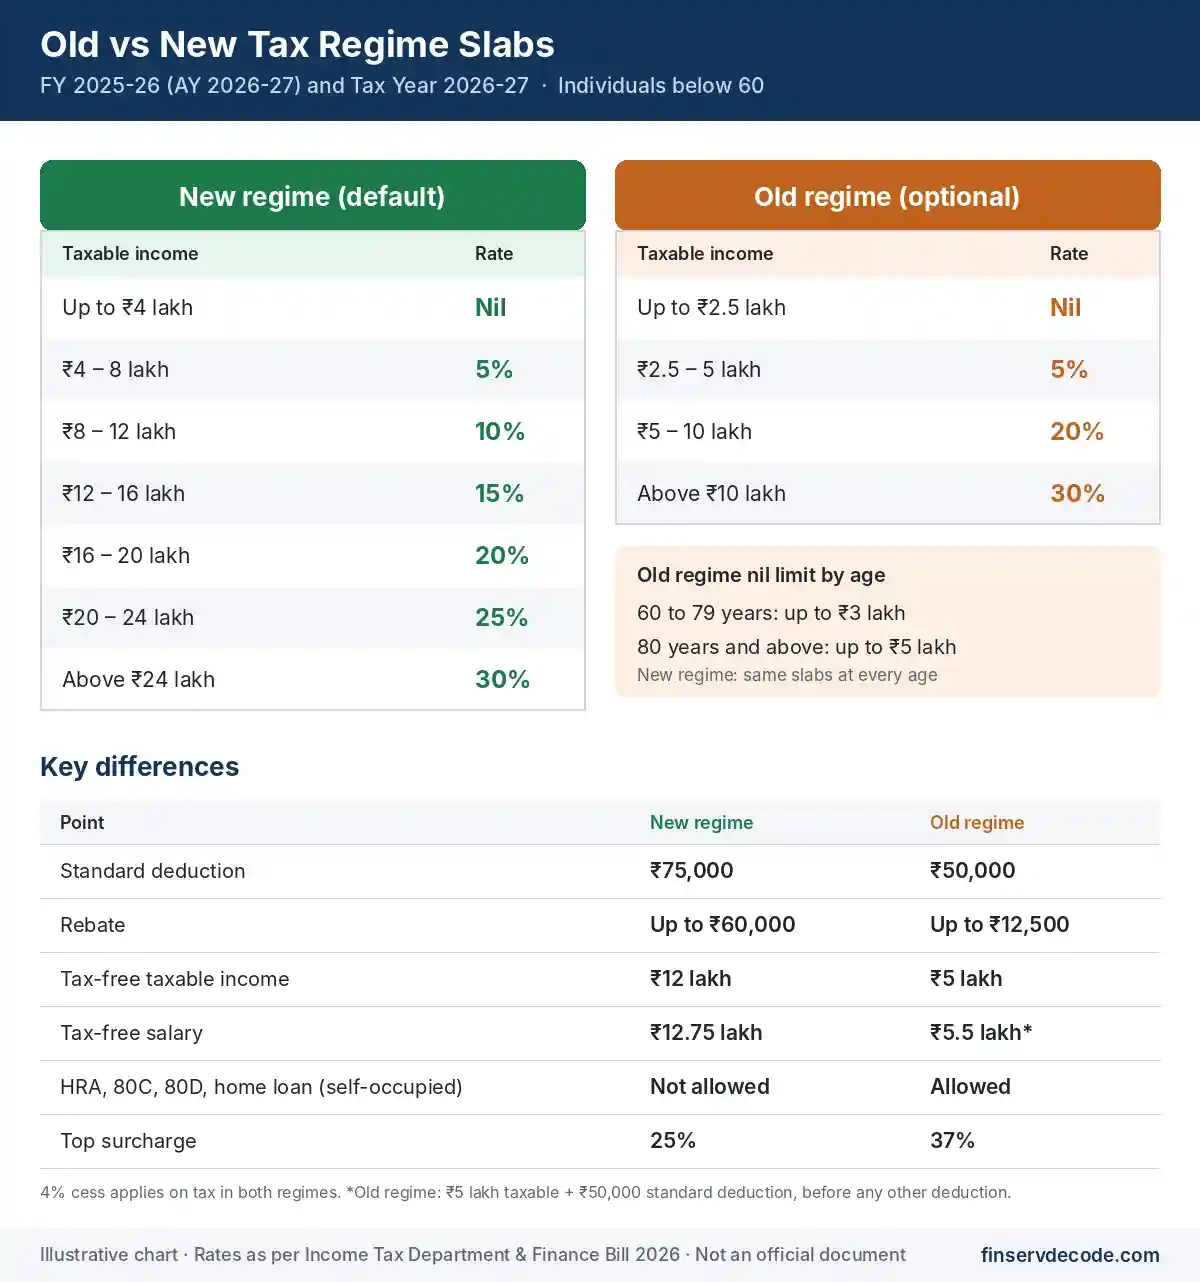
New tax regime slabs for FY 2026-27 (Section 202)
These are the new tax regime slabs for FY 2026-27, which are the same as those for FY 2025-26 under Section 115BAC.
| Taxable Income | Rate | Tax at the Top of the Slab (Before Cess) |
|---|---|---|
| Up to ₹4,00,000 | Nil | ₹0 |
| ₹4,00,001 to ₹8,00,000 | 5% | ₹20,000 |
| ₹8,00,001 to ₹12,00,000 | 10% | ₹60,000 |
| ₹12,00,001 to ₹16,00,000 | 15% | ₹1,20,000 |
| ₹16,00,001 to ₹20,00,000 | 20% | ₹2,00,000 |
| ₹20,00,001 to ₹24,00,000 | 25% | ₹3,00,000 |
| Above ₹24,00,000 | 30% | ₹3,00,000 + 30% of the amount above ₹24 lakh |
The same slabs apply at every age. A 70-year-old pensioner and a 25-year-old employee pay the same tax on the same income under the new regime. Add a 4% health and education cess on the tax, plus surcharge if your income is above ₹50 lakh.
Old regime tax slab FY 2025-26 (below 60)
The old tax regime slabs have stayed the same for years. Here is the old regime tax slab for FY 2025-26, which continues for Tax Year 2026-27:
| Taxable Income | Rate | Tax at the Top of the Slab (Before Cess) |
|---|---|---|
| Up to ₹2,50,000 | Nil | ₹0 |
| ₹2,50,001 to ₹5,00,000 | 5% | ₹12,500 |
| ₹5,00,001 to ₹10,00,000 | 20% | ₹1,12,500 |
| Above ₹10,00,000 | 30% | ₹1,12,500 + 30% of the amount above ₹10 lakh |
A resident individual with taxable income up to ₹5 lakh gets a rebate of up to ₹12,500, so the tax at ₹5 lakh becomes nil. While the old slabs have stayed put, the new regime has been changed every few Budgets, which is why the gap between the two keeps moving.
Old regime slabs for senior and super senior citizens
Only the old regime gives a higher exemption limit by age. The Income Tax Department’s senior citizens page lists these slabs:
| Taxable Income | Senior Citizen (60 to 79) | Super Senior Citizen (80+) |
|---|---|---|
| Up to ₹3,00,000 | Nil | Nil |
| ₹3,00,001 to ₹5,00,000 | 5% | Nil |
| ₹5,00,001 to ₹10,00,000 | 20% | 20% |
| Above ₹10,00,000 | 30% | 30% |
| Tax at ₹10 lakh (before cess) | ₹1,10,000 | ₹1,00,000 |
| Tax at ₹10 lakh (with 4% cess) | ₹1,14,400 | ₹1,04,000 |
How a ₹12.75 Lakh Salary Becomes Tax-Free in the New Regime
Two things work together. First, a salaried person gets the ₹75,000 standard deduction, so a ₹12.75 lakh salary becomes ₹12 lakh of taxable income. Second, a resident individual with taxable income up to ₹12 lakh gets a rebate of up to ₹60,000, which is exactly the tax on ₹12 lakh (₹20,000 + ₹40,000). The tax payable is nil. From Tax Year 2026-27, this rebate is in Section 156 of the Income-tax Act, 2025, which replaced Section 87A.
What if you earn slightly more than ₹12 lakh? You do not suddenly owe ₹60,000 or more. Section 156(2)(b) limits your tax to the amount by which your income crosses ₹12 lakh. Working from the slab rates, this marginal relief ends at a taxable income of about ₹12,70,588, which is a salary of about ₹13.45 lakh after the standard deduction.
| Taxable Income | Tax as per Slabs | Tax After Marginal Relief | Payable with 4% Cess |
|---|---|---|---|
| ₹12,00,000 | ₹60,000 | ₹0 | ₹0 |
| ₹12,10,000 | ₹61,500 | ₹10,000 | ₹10,400 |
| ₹12,50,000 | ₹67,500 | ₹50,000 | ₹52,000 |
| ₹12,70,000 | ₹70,500 | ₹70,000 | ₹72,800 |
| ₹12,75,000 | ₹71,250 | No relief (₹71,250) | ₹74,100 |
The rebate has three limits:
- It is only for resident individuals, so NRIs do not get it.
- It does not cover income tax taxed at special rates, such as short-term gains on listed shares and equity funds or long-term capital gains. Section 156(3) limits the rebate to tax at the Section 202(1) slab rates.
- It is not available to a Hindu Undivided Family. An HUF’s tax slabs and rebate rules work differently, so an HUF pays tax above ₹4 lakh even in the new regime.
Default Tax Regime Meaning and What “Opting Out” Means
The default tax regime meaning is simple: if you do nothing, the new regime applies. Since FY 2023-24, your income is taxed under Section 115BAC (Section 202 from Tax Year 2026-27) unless you choose otherwise. The old regime is now the optional tax regime, and you get it only if you opt for it.
The wording in the ITR and in your Form 16 confuses many people. The ITR does not ask “old or new?”. It asks whether you are opting out of the new regime. In Form 16, the same question appears as “Whether opting out of taxation u/s 115BAC(1A)?”. Here is what the terms mean:
| What You See | What It Means |
|---|---|
| Opting out: No | You stay in the new (default) regime |
| Opting out: Yes | You are choosing the old regime and can claim its deductions |
| Default tax regime | New regime under Section 115BAC / Section 202 |
| Optional tax regime or regular tax regime | Old regime |
| Opted out of the default tax regime | You chose the old regime for that year |
If you are checking your Form 16, the regime your employer used for TDS is shown in that “opting out” row of Part B. It reflects what you told your employer, not your final choice.
Deductions Allowed in the New Tax Regime
The new regime removes most deductions, but not all. The Income Tax Department’s FAQ on the two regimes says Chapter VI-A deductions cannot be claimed: “except deduction u/s 80CCD(2)/80CCH/80JJAA”. These are the deductions allowed in the new tax regime for a salaried person or pensioner:
| Deduction or Exemption | Section (1961 Act) | What You Get in the New Regime |
|---|---|---|
| Standard deduction on salary or pension | 16(ia) | ₹75,000 or the salary, whichever is lower |
| Employer’s contribution to NPS | 80CCD(2) | Up to 14% of salary (basic + DA) |
| Family pension deduction | 57(iia) | One-third of family pension or ₹25,000, whichever is lower |
| Agniveer Corpus Fund contribution | 80CCH(2) | Government’s contribution, fully deductible |
| Interest on loan for a let-out house | 24(b) | Full interest against rent; a resulting loss cannot be set off against other income |
| Gratuity, leave encashment, retrenchment compensation | 10(10), 10(10AA), 10(10B) | Exempt within their limits, same as the old regime |
| Transport allowance for a disabled employee | 10(14) | Exempt as prescribed |
| Deduction for new employees (business) | 80JJAA | Available to eligible businesses |
Is 80D allowed in the new regime? No. Health insurance premiums for yourself, your family, or your parents are not deductible. Is the ₹75,000 standard deduction allowed? Yes. Section 19 of the Income-tax Act, 2025 keeps it at ₹75,000 where tax is worked out under Section 202(1), and ₹50,000 in other cases. Professional tax paid on salary is not deductible in the new regime.
80CCD(2) in the new tax regime: a higher limit than the old
This is one place where the new regime is more generous. Under Section 80CCD(2), the deduction for a private employer’s NPS contribution is capped at 10% of salary in the old regime. The proviso raises it to 14% when you are taxed under Section 115BAC. For government employees, the limit is 14% in both regimes. So 80CCD(2) in the new tax regime can be worth more than in the old one:
| Basic + DA per Year | Old Regime Limit (Private Employer, 10%) | New Regime Limit (14%) | Extra Deduction in New Regime |
|---|---|---|---|
| ₹6,00,000 | ₹60,000 | ₹84,000 | ₹24,000 |
| ₹10,00,000 | ₹1,00,000 | ₹1,40,000 | ₹40,000 |
| ₹15,00,000 | ₹1,50,000 | ₹2,10,000 | ₹60,000 |
This helps only if your employer actually puts in that much, usually through a flexible pay structure. Since it is a deduction, the tax you save is the extra deduction multiplied by your slab rate, not the full amount. Your own NPS contribution under Section 80CCD(1B), the extra ₹50,000, is allowed only in the old regime. From Tax Year 2026-27, this deduction has a new section number under the Income-tax Act, 2025, so check the limit under the new section when you file for that year.
The family pension deduction follows the same pattern. Under Section 57(iia), it is capped at ₹15,000 in the old regime and ₹25,000 in the new regime.
Old Tax Regime Deductions You Give Up in the New Regime
These are the claims you lose by staying in the new regime. There is no single overall cap on old tax regime deductions. Each item has its own limit, and your total depends on which ones apply to you.
| Deduction or Exemption | Section (1961 Act) | Limit |
|---|---|---|
| PPF, EPF (own share), ELSS, life insurance, home loan principal, tuition fees | 80C | ₹1,50,000 in total |
| Health insurance (self, spouse, children) | 80D | ₹25,000 (₹50,000 if a senior citizen is covered) |
| Health insurance for parents | 80D | Another ₹25,000 (₹50,000 if parents are senior citizens) |
| Own NPS contribution, over and above 80C | 80CCD(1B) | ₹50,000 |
| House Rent Allowance | 10(13A) | Lowest of actual HRA, rent minus 10% of salary, and 50% or 40% of salary |
| Leave Travel Allowance | 10(5) | Actual domestic travel fare, two journeys in a block of four years |
| Interest on home loan, self-occupied house | 24(b) | ₹2,00,000 |
| Interest on education loan | 80E | Full interest, for up to 8 years |
| Savings account interest (below 60) | 80TTA | ₹10,000 |
| Deposit interest for senior citizens | 80TTB | ₹50,000 |
| Donations to eligible funds and charities | 80G | 50% or 100%, depending on the fund |
| Professional tax | 16(iii) | Actual amount paid |
From Tax Year 2026-27, these deductions carry new section numbers under the Income-tax Act, 2025. For example, 80C becomes Section 123, and 80D becomes Section 126. When you claim them for that year, check the limits and conditions under the new section. The Tax Year under the Income-tax Act, 2025 is the reason the numbering and year labels changed.
Count only what is real. Rent you actually pay, an EMI you actually service, a premium you actually paid. An investment made only to cross the break-even point locks up your money and may still lose to the new regime.
Home Loan Interest in the New Tax Regime
Here is how home loan interest in the new tax regime works. For a house you live in (self-occupied), it is not allowed. The Income Tax Department’s FAQ says interest on borrowed capital for a self-occupied property is not allowed as a deduction in the new regime. The principal repayment, which comes under Section 80C, is not available either. Both need the old regime.
For a let-out house, the interest is allowed, with one catch. You can deduct the full interest from the rent you earn, with no ₹2 lakh cap. But if the interest is more than the rent, the resulting loss under “Income from house property” cannot be set off against your salary or any other income, and you cannot carry it forward.
In the old regime, up to ₹2 lakh of that loss can be set off against other income in the same year, and the rest can be carried forward for up to 8 years against future house property income. Section 202(2)(b)(ii) of the Income-tax Act, 2025 keeps the same set-off restriction.
| Home Loan Situation | Old Regime | New Regime |
|---|---|---|
| Self-occupied: interest | Up to ₹2 lakh | Not allowed |
| Self-occupied: principal (80C) | Within ₹1.5 lakh | Not allowed |
| Let-out: interest | Full, against rent | Full, against rent |
| Let-out: loss (interest more than rent) | Up to ₹2 lakh against other income; the rest carried forward | Lost. No set-off, no carry forward |
A home loan pushes you towards the old regime, but it does not decide the matter on its own. ₹2 lakh of interest plus ₹1.5 lakh of 80C is ₹3.5 lakh. Add the ₹50,000 standard deduction, and you are at ₹4 lakh, still short of the ₹5.94 lakh break-even at a ₹15 lakh salary. A home loan usually wins only when it comes with other large deductions.
Who Should Pick the Old Regime, and Who Should Stay in the New One
For a salaried employee, two questions settle most cases: do you claim HRA, and do you pay a home loan on a house you live in? Without either, your deductions rarely cross the break-even point, which is why the new regime suits a large share of salaried people.
The old regime is worth working out if you are:
- A tenant in a big city claiming a large HRA exemption, plus full 80C and 80D
- A home loan borrower on your own house who also claims 80C, 80D and your own NPS
- Paying health insurance for senior citizen parents
- Someone whose real deductions add up to more than the break-even for your salary
The new regime usually costs less if you are:
- An employee with no HRA claim and no home loan on the house you live in
- A resident employee earning up to ₹12.75 lakh with no special-rate income
- Someone whose employer contributes NPS up to 14% of salary
- Someone whose deductions are close to the break-even, and who would rather keep fewer records
How to check your own numbers in 4 steps
- Add up your gross income. Take your salary from Form 16 or payslips, then add interest, rent, capital gains, and any other income. Check them against your Annual Information Statement (AIS).
- Work out the new regime tax. Subtract ₹75,000 from salary or pension, apply the new slabs, then the rebate or marginal relief, then 4% cess. Or read it from the break-even table above.
- List your real old regime deductions. The ₹50,000 standard deduction, HRA exemption, 80C, 80D, 80CCD(1B), home loan interest, 80E, 80G and professional tax. Count only what you have paid or will actually pay this year.
- Compare. If your total from step 3 is above the break-even for your salary, work out the old regime tax and confirm it is lower. The Income Tax Department’s tax calculator lets you check both figures.
Which Tax Regime Is Better for Senior Citizens and Pensioners?
When asking which tax regime is better for senior citizens, start with what seniors lose in the new regime. The old regime gives them two benefits others don’t get: a higher exemption limit (₹3 lakh, or ₹5 lakh at 80 and above) and a ₹50,000 deduction on deposit interest under Section 80TTB. The new regime has neither, and no separate slabs for seniors. Even so, the new regime often comes out ahead, because its ₹4 lakh nil slab and ₹12 lakh rebate cover more income.
Take a 65-year-old resident with a pension of ₹9 lakh and FD interest of ₹3 lakh, who pays a ₹50,000 health insurance premium. The figures are illustrative.
| Item | Old Regime (Senior Slabs) | New Regime |
|---|---|---|
| Pension after standard deduction | ₹8,50,000 | ₹8,25,000 |
| FD interest | ₹3,00,000 | ₹3,00,000 |
| Less: 80TTB | ₹50,000 | Not allowed |
| Less: 80D (senior citizen) | ₹50,000 | Not allowed |
| Taxable income | ₹10,50,000 | ₹11,25,000 |
| Tax including 4% cess | ₹1,30,000 | Nil (rebate) |
At a higher income, the gap stays large. With a pension of ₹12 lakh and interest of ₹4 lakh, the new regime tax is ₹1,13,100, against ₹2,54,800 in the old regime with the same two deductions. The old regime helps a senior mainly when there are other big deductions, such as home loan interest or large 80C investments.
One more rule for older seniors: a resident aged 75 or more, whose only income is pension and interest from the same bank that pays the pension, may not need to file a return at all. They must give that bank the required declaration, and the bank then deducts the tax under Section 194P, as the senior citizens page explains.
What You Lose in the New Regime (and the Old Regime’s Own Cost)
The new regime is cheaper for many taxpayers, but it has costs the slab table does not show:
- No tax benefit for insurance or health cover. With 80C and 80D gone, a family with a large term plan, PPF, and health cover for senior parents gets nothing back on those payments.
- HRA is lost, however high your rent. A tenant in a metro paying ₹30,000 or more a month gives up an exemption that can exceed ₹2.5 lakh a year.
- A house property loss is wasted. A let-out flat with a big loan often shows a loss in the early years. In the new regime, that loss reduces nothing.
- Seniors lose 80TTB and their higher exemption limit.
- Professional tax and LTA are not allowed.
- No relief by age. A super senior citizen pays exactly what a young employee pays on the same income.
The old regime has its own cost: paperwork. You need rent receipts, the landlord’s PAN when annual rent is above ₹1 lakh, premium receipts, investment proofs, and the bank’s interest certificate, and you must keep them in case the department asks. If both regimes give almost the same tax, the lighter paperwork of the new regime is a fair reason to stay in it.
Common Mistakes When Choosing a Tax Regime
Most wrong choices come from a few repeated errors, not from the slab rates themselves.
- Deciding on the gross salary alone. “I earn ₹15 lakh, so the old regime must be better” skips the real test. What matters is your total deductions compared with the break-even for your salary.
- Counting deductions you don’t actually have. Including an 80C limit you never use, or HRA when you live in your own house, makes the old regime look better on paper than it is.
- Forgetting the standard deduction difference. The new regime gives ₹75,000, and the old gives ₹50,000. That ₹25,000 gap is already built into the break-even table, so don’t add it twice.
- Buying investments only to cross the break-even. If you need an extra ₹1 lakh of investments just to come out ₹7,000 ahead of the new regime, you are locking up ₹1 lakh for a small net gain. Compare that gain with what the money could do elsewhere.
- Treating the employer declaration as final. It only decides your TDS. Salaried people make the binding choice in the ITR, and it can differ.
- Missing the due date. Filing late takes away the old regime for that year, even if it would have saved you tax.
- Ignoring special-rate income. Capital gains taxed at special rates are not covered by the ₹12 lakh rebate, so “tax-free up to ₹12 lakh” may not hold if you sold shares or mutual funds during the year.
Surcharge Under the Old vs New Tax Regime
Surcharge is an extra charge on the tax itself, and it applies only when income is above ₹50 lakh. The rates are the same in both regimes up to ₹5 crore. Above that, the new regime caps it at 25%.
| Total Income | Old Regime Surcharge | New Regime Surcharge |
|---|---|---|
| Up to ₹50 lakh | Nil | Nil |
| Above ₹50 lakh to ₹1 crore | 10% | 10% |
| Above ₹1 crore to ₹2 crore | 15% | 15% |
| Above ₹2 crore to ₹5 crore | 25% | 25% |
| Above ₹5 crore | 37% | 25% |
In both regimes, surcharge on capital gains under Sections 111A, 112 and 112A, and on dividends, is capped at 15%. Marginal relief also applies at each surcharge threshold, so crossing ₹50 lakh by a small amount does not cost you more than the extra income. For incomes above ₹5 crore, the 12-point gap in the top surcharge rate (37% vs 25%) weighs heavily in favour of the new regime, but work out both, including any special-rate income, before deciding.
Can We Switch Between Old and New Tax Regime Every Year?
Can we switch between the old and new tax regime every year? Yes, if you have no business or professional income. Salaried people, pensioners, and people with only interest, rent, or capital gains can choose again every year in their income tax return. With business or professional income, switching is limited.
Salaried employees: your employer declaration vs your ITR choice
At the start of the year, your employer asks which regime you want for TDS. The Income Tax Department’s FAQ says that if you don’t tell your employer, TDS is deducted under the new regime, and that telling your employer is not the same as exercising the option. The real choice is made in your ITR.
- Tell your employer your intended regime at the start of the year, so your TDS matches it. Employers generally apply this declaration to the whole year’s TDS.
- Submit your proofs on time if you chose the old regime with your employer. Each employer sets its own deadline for investment and rent proofs.
- Make the final choice in your ITR. Select “Yes” for opting out of the new regime if you want the old one, or “No” to stay in the new regime. This can differ from what you told your employer.
- Settle the difference. If your final tax is lower than the TDS, you get a refund. If it is higher, pay the balance as self-assessment tax before filing.
Watch the due date. The old regime can be chosen only in a return filed on or before the due date under Section 139(1). A belated return is taxed under the new regime. Under the Income-tax Act, 2025, Section 202(4) ties the option to the return furnished under Section 263(1) in the same way.
Business or professional income: Form 10-IEA applicability
Form 10-IEA applicability is limited to people with business or professional income. For FY 2025-26 (AY 2026-27), such a person must file Form 10-IEA on or before the Section 139(1) due date to choose the old regime, as the Department’s business and profession page explains. People filing ITR-1 or ITR-2 do not need the form; they simply tick the opt-out option in the return.
After leaving the new regime, a person with business income can return to it only once. After that return, they cannot opt out again while they have business income. Form 10-IEA filed for a year cannot be withdrawn for that same year. If the business income stops, the year-by-year choice that salaried people have opens up again.
From Tax Year 2026-27, Section 202(4) keeps the same structure: the option must be exercised by the return due date, and it can be withdrawn only once. The forms published so far under the Income-tax Rules, 2026 do not show a renumbered Form 10-IEA, so check what the e-filing portal and ITR utility ask for when they open in 2027. Form 10-IE, which was used to opt into the new regime before it became the default, is no longer needed.
Is the Old Tax Regime Ending? What Changes From Tax Year 2026-27
For this decision, very little changes. From 1 April 2026, the new regime is governed by Section 202 of the Income-tax Act, 2025 instead of Section 115BAC, and the rebate by Section 156 instead of Section 87A. The slab rates, the ₹12 lakh rebate limit, the ₹75,000 standard deduction, and the 14% employer NPS limit for the new regime all stay the same.
The old regime has not been discontinued. Section 202(4) still lets individuals opt out of the new regime, and the Finance Bill, 2026 kept the old regime’s rates unchanged.
One labelling point is confusing: the new Act does not use the term “AY 2027-28”. Income earned from 1 April 2026 to 31 March 2027 belongs to Tax Year 2026-27, and its return is filed in 2027. For how slabs, heads of income, and deductions fit together, see how income tax works in India.
Frequently Asked Questions
Is a ₹12 lakh salary tax-free in the new regime?
Yes, for a resident individual. After the ₹75,000 standard deduction, a ₹12 lakh salary becomes ₹11.25 lakh of taxable income, and the rebate makes the tax nil. In fact, a salary of up to ₹12.75 lakh is tax-free for a resident individual with no special-rate income.
Can I claim HRA or 80D in the new tax regime?
No. The HRA exemption under Section 10(13A) and health insurance premiums under Section 80D can be claimed only in the old regime.
Can my employer force a tax regime on me?
No. Your employer deducts TDS based on the regime you declare, or the new regime if you declare nothing. You make the final choice in your ITR, and any difference is settled as a refund or extra tax.
What happens if I don’t choose a regime in my ITR?
You are taxed under the new regime because it is the default. The old regime applies only if you select the opt-out option.
Can I choose the old regime in a belated return?
No. For individuals without business income, the old regime must be chosen in a return filed by the due date under Section 139(1). A belated return is taxed under the new regime.
Which tax regime is better for NRIs?
NRIs do not get the Section 87A or Section 156 rebate in either regime, so the new regime is not tax-free up to ₹12 lakh for them. Compare both using the slab rates and the deductions NRIs can claim.
Is the 87A rebate available on capital gains in the new regime?
No. The rebate covers only tax at the normal slab rates. Tax on special-rate income, such as short-term gains on listed shares, is payable even if your total income is below ₹12 lakh.
Is the old tax regime being discontinued?
No. The Income-tax Act, 2025 keeps the option to opt out of the new regime under Section 202(4), and the Finance Bill, 2026 did not change the old regime’s rates. You can still choose it for Tax Year 2026-27.
What is the tax on a ₹20 lakh salary in the new regime?
For a resident individual below 60 with only salary income, it is ₹1,92,400 including cess, on taxable income of ₹19.25 lakh. To pay the same tax in the old regime, you would need about ₹7.58 lakh of total deductions.
What is the difference between Form 10-IE and Form 10-IEA?
Form 10-IE was used to opt into the new regime when the old one was the default. Form 10-IEA is used by people with business or professional income to opt out of the new regime, which is now the default.
Conclusion
In the new tax regime vs old tax regime choice, the slab rates are fixed and the same for FY 2025-26 and Tax Year 2026-27. The only number you control is your deductions. Compare your real total with the break-even for your salary: about ₹5.94 lakh at ₹15 lakh, about ₹7.58 lakh at ₹20 lakh, and about ₹8.5 lakh from ₹25 lakh upward.
Below that figure, the new regime costs less, and up to a ₹12.75 lakh salary it costs a resident individual nothing. Above it, the old regime can save tax, mainly for people with metro HRA, a home loan on their own house, full 80C and 80D, or senior parents to insure. Salaried people can check again every year in the ITR. With business income, treat the switch as a long-term decision, because you get only one return to the new regime.
Disclaimer: This article is for general information only and is not tax advice. Tax figures are illustrative. They assume a resident individual with the stated income and deductions, include 4% cess, and were worked out by finservdecode.com from the slab rates on the Income Tax Department’s website and the Finance Bill, 2026 Memorandum, as checked as of now. Your actual tax depends on your full income, residential status, age, and documents. Rules, section numbers, and forms under the Income-tax Act, 2025 and the Income-tax Rules, 2026 can change through notifications or Finance Acts. The charts in this article are illustrative and are not official documents. Please confirm your figures on the Income Tax Department’s calculator or with a Chartered Accountant before choosing a regime.