The best SBI credit cards is the one that pays you back on the spending you already do, at a fee you can get reversed. For most online shoppers, that is the Cashback SBI Card, which pays 5% on eligible online spends with a cap of ₹2,000 per statement. If you want a low fee, SimplyCLICK (for online partners) or SimplySAVE (for dining and groceries) costs ₹499, and the renewal fee is reversed once you spend ₹1 lakh in a year. For regular fuel at BPCL pumps, look at BPCL SBI Card OCTANE or the cheaper BPCL SBI Card. For travel with lounge access, SBI Card ELITE and SBI Card MILES ELITE lead, and SBI Card PRIME does the same job at a lower fee.
No card wins for everyone, because each one has its own caps, excluded categories, and fee-reversal spend. This guide compares 16 SBI cards across the needs people search for most: online shopping, travel and lounges, fuel, UPI, no annual fee, beginners, and premium use. Fees, fee reversals, foreign currency markup, and interest rates are taken from SBI Card’s Most Important Terms and Conditions (MITC), dated 21 August 2026. Card features come from each card’s page on sbicard.com. SBI Card changes these through notices, so check the card page before you apply.
Best SBI Credit Cards by Need: Quick Overview
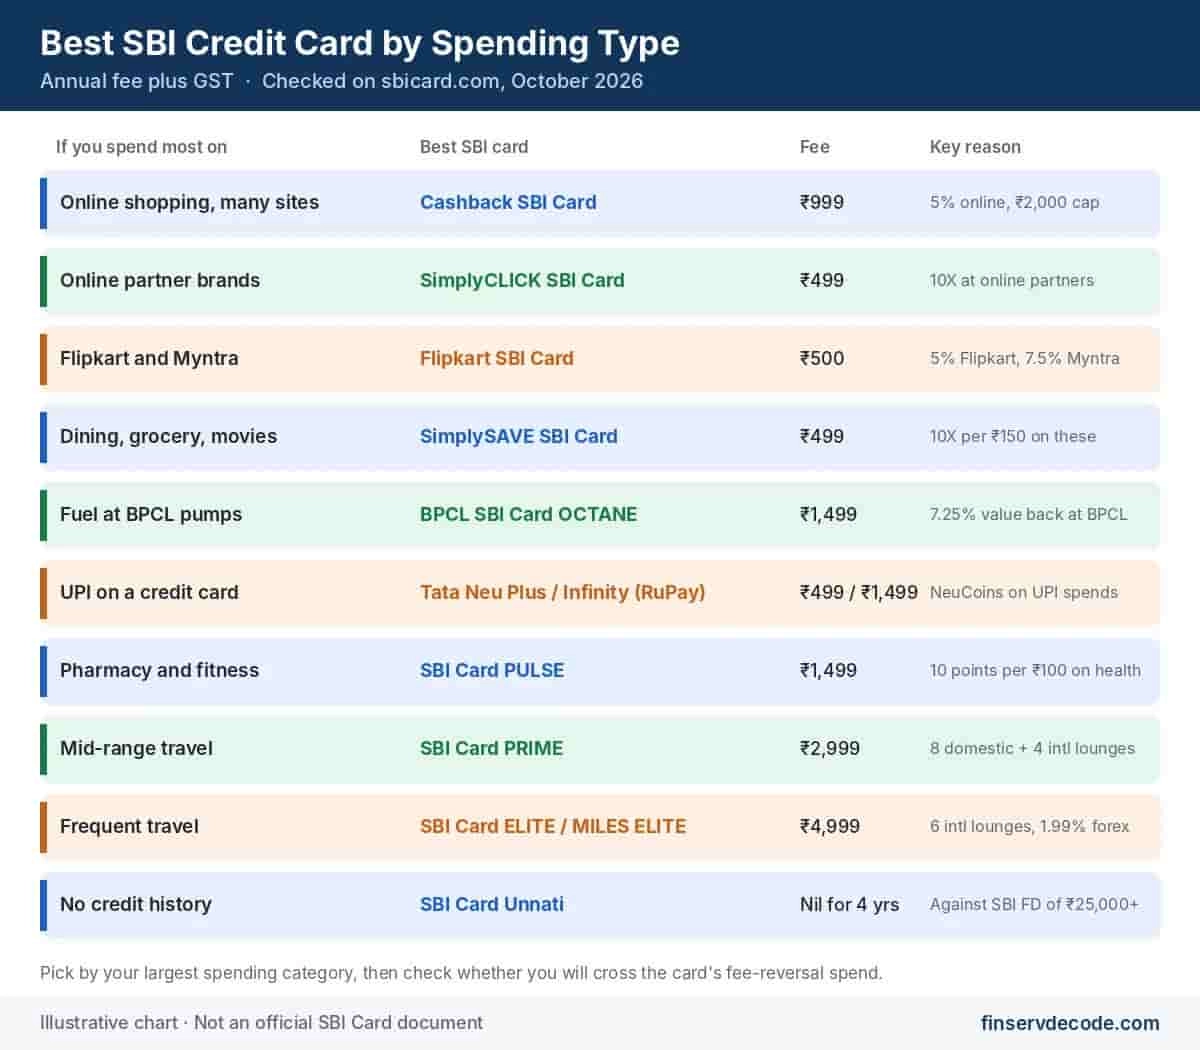
| If You Want | Best SBI Card | Annual Fee | Why It's Best |
|---|---|---|---|
| Cashback on online shopping | Cashback SBI Card | ₹999 | 5% on eligible online spends, 1% offline; ₹2,000 cap on each, ₹4,000 in total per statement |
| A low-fee first card for online spends | SimplyCLICK SBI Card | ₹499 | 10X points at listed online partners such as BookMyShow, Cleartrip and Myntra; fee reversed at ₹1 lakh |
| Rewards on dining, groceries, and movies | SimplySAVE SBI Card | ₹499 | 10 points per ₹150 in these categories; fee reversed at ₹1 lakh |
| Flipkart and Myntra shopping | Flipkart SBI Card | ₹500 | 5% on Flipkart, 7.5% on Myntra |
| Fuel at BPCL pumps | BPCL SBI Card OCTANE | ₹1,499 | 7.25% value back at BPCL; 4 domestic lounge visits |
| Travel with lounge access | SBI Card ELITE or MILES ELITE | ₹4,999 | 8 domestic and 6 international lounge visits a year; 1.99% forex markup |
| Lounge access at a mid-range fee | SBI Card PRIME | ₹2,999 | 8 domestic and 4 international visits; fee reversed at ₹3 lakh |
| UPI payments on a credit card | Tata Neu Plus or Infinity SBI Card (RuPay) | ₹499 / ₹1,499 | NeuCoins on UPI spends through the RuPay variant |
| No annual fee for the first years | SBI Card Unnati | Nil for 4 years | Issued against a fixed deposit; ₹499 from year 5 |
| Top-end premium card | AURUM | ₹9,999 | Fee reversed at ₹12 lakh; 1.99% forex markup |
All fees are before 18% GST. Cashback and reward rates apply only to eligible transactions, and a fee reversal applies to the renewal fee after you cross the yearly spend, not to the first-year fee.
Which SBI Credit Card Is Best for You?
Which SBI credit card is best for you comes down to two numbers: where most of your card spending goes, and how much you spend on the card in a year. Settle both before you look at welcome gifts, because a gift is a one-time benefit and the fee comes back every year.
Step 1: Where does most of your money go?
| Most of Your Card Spending Is On | Best SBI Card | Also Consider |
|---|---|---|
| Many different shopping websites and apps | Cashback SBI Card | SimplyCLICK |
| BookMyShow, Cleartrip, Myntra, and other SimplyCLICK partners | SimplyCLICK SBI Card | Cashback SBI Card |
| Flipkart and Myntra | Flipkart SBI Card | Cashback SBI Card |
| Tata Neu, BigBasket, Croma and other Tata brands, or UPI | Tata Neu Plus or Infinity SBI Card | None |
| Groceries, dining out and movies | SimplySAVE SBI Card | SBI Card PRIME |
| Petrol and diesel at BPCL pumps | BPCL SBI Card OCTANE (heavy use) or BPCL SBI Card | None |
| Pharmacy, fitness and sports | SBI Card PULSE | None |
| Flights, hotels and airport lounges | SBI Card MILES ELITE or ELITE | SBI Card PRIME |
| You are new to credit or have no credit history | SBI Card Unnati (against an FD) | SimplySAVE or SimplyCLICK |
Step 2: Will you cross the fee-reversal spend?
| Your Yearly Card Spend | Cards Whose Renewal Fee Is Reversed at That Level |
|---|---|
| ₹1 lakh | SimplyCLICK, SimplySAVE, BPCL SBI Card, Tata Neu Plus (Unnati has no fee for 4 years) |
| ₹2 lakh | Add Cashback SBI Card, BPCL SBI Card OCTANE and SBI Card PULSE |
| ₹3 lakh to ₹3.5 lakh | Add SBI Card PRIME, Tata Neu Infinity, PhonePe SBI Card SELECT BLACK and Flipkart SBI Card (₹3.5 lakh) |
| ₹10 lakh and above | Add SBI Card ELITE (₹10 lakh), AURUM (₹12 lakh), and SBI Card MILES ELITE (₹15 lakh) |
Only spends that count under the card’s terms go towards the reversal, so check the excluded categories first. If you will not reach the reversal amount, you pay the fee plus GST every year. In that case, add up only the benefits you will really use. This is why a ₹4,999 travel card rarely suits someone who spends ₹2 lakh a year, however good its lounge list looks.
SBI Credit Card Comparison Table
This SBI credit card comparison puts all 16 cards side by side, so it also works as a quick SBI credit card list with the SBI credit card names as SBI Card uses them. SBI Card’s own credit cards page shows its current range by category. The annual fee is before GST, and the reversal column shows the yearly spend at which SBI Card reverses the renewal fee, as listed in the MITC.
| Card | Annual Fee | Renewal Fee Reversed At | Main Benefit | Lounge Visits (per Year) |
|---|---|---|---|---|
| Cashback SBI Card | ₹999 | ₹2 lakh | 5% online, 1% offline cashback | None |
| SimplyCLICK SBI Card | ₹499 | ₹1 lakh | 10X points at online partners, 5X at other online partners | None |
| SimplySAVE SBI Card | ₹499 | ₹1 lakh | 10X points on dining, movies, groceries, departmental stores | None |
| Flipkart SBI Card | ₹500 | ₹3.5 lakh | 5% Flipkart, 7.5% Myntra | None |
| Tata Neu Plus SBI Card | ₹499 | ₹1 lakh | 2% NeuCoins on Tata Neu, 1% elsewhere including UPI | 4 domestic |
| Tata Neu Infinity SBI Card | ₹1,499 | ₹3 lakh | 5% NeuCoins on Tata Neu, 1.5% elsewhere including UPI | 8 domestic + 4 international |
| BPCL SBI Card | ₹499 | ₹1 lakh | 4.25% value back at BPCL | None |
| BPCL SBI Card OCTANE | ₹1,499 | ₹2 lakh | 7.25% value back at BPCL | 4 domestic |
| SBI Card PULSE | ₹1,499 | ₹2 lakh | 10 points per ₹100 on pharmacy, sports, dining, movies | 4 domestic |
| PhonePe SBI Card SELECT BLACK | ₹1,499 | ₹3 lakh | Accelerated points on PhonePe spends; monthly caps from 1 July 2026 | 4 domestic |
| SBI Card PRIME | ₹2,999 | ₹3 lakh | 10 points per ₹100 on dining, groceries, departmental stores, movies | 8 domestic + 4 international |
| SBI Card ELITE | ₹4,999 | ₹10 lakh | Free movie tickets, milestone bonus points | 8 domestic + 6 international |
| SBI Card MILES ELITE | ₹4,999 | ₹15 lakh | 6 Travel Credits per ₹200 on travel | 8 domestic (+ spend-linked extra) + 6 international |
| Air India SBI Signature Card | ₹4,999 | No reversal listed | 10 points per ₹100 on Air India tickets | 8 domestic |
| AURUM | ₹9,999 | ₹12 lakh | 4 points per ₹100, redeemed on AURUM’s own portal | As per card terms |
| SBI Card Unnati | Nil for 4 years, then ₹499 | Not applicable | Secured against a fixed deposit | None |
Tata Neu cards give domestic lounge visits only after a spend condition in the previous quarter (₹50,000 for Plus, ₹75,000 for Infinity).
Reward points, NeuCoins, Travel Credits, and cashback are different reward currencies, so compare them by the redemption you will actually use, not by the headline number. If you want to know what the wider range of SBI credit cards includes beyond these 16, including co-brand cards, it is covered in a separate overview.
Best SBI Credit Card for Online Shopping
For the best SBI credit card for online shopping, three cards compete: Cashback for any website, SimplyCLICK for its partner brands, and Flipkart SBI for Flipkart and Myntra.
| Point | Cashback SBI Card | SimplyCLICK SBI Card | Flipkart SBI Card |
|---|---|---|---|
| Annual fee / reversed at | ₹999 / ₹2 lakh | ₹499 / ₹1 lakh | ₹500 / ₹3.5 lakh |
| Online return | 5% on eligible online spends, any merchant | 10X points at partners (2.5%), 5X on other online (1.25%) | 5% on Flipkart, 7.5% on Myntra |
| Offline return | 1% | 1 point per ₹100 (0.25%) | 1% |
| Cap | ₹2,000 online + ₹2,000 offline = ₹4,000 per statement | As per card terms | As per card terms |
| Extra | Cashback credited to the statement | E-vouchers at online spend milestones | Welcome gift card on fee payment |
The Cashback SBI Card’s revised terms from 1 April 2026 cap cashback at ₹2,000 on online and ₹2,000 on offline spends per statement. They also exclude several categories, including utilities, insurance, fuel, rent, wallets, school and education payments, jewellery, railways, gaming, tolls and government payments, along with merchant EMI and Flexipay EMI. How the card pays out and where it falls short is explained in the Cashback SBI Card’s full terms and exclusions.
SimplyCLICK’s 10X partners include Apollo 24×7, BookMyShow, Cleartrip, Domino’s, IGP, Myntra, Netmeds and Yatra. Swiggy moved from 10X to 5X on 1 April 2025, so it now earns the normal online rate. Partners change from time to time, so check the current list on the SimplyCLICK card page before you shop. The SimplyCLICK card’s partner rewards and milestones are covered in detail separately.
Worked example: ₹15,000 a month spent online
This is an illustration with assumed figures. Someone spends ₹8,000 a month at SimplyCLICK partners and ₹7,000 on other websites, all in eligible categories.
| Card | Monthly Value | Yearly Value | Notes |
|---|---|---|---|
| SimplyCLICK | ₹200 (800 points) + ₹87.50 (350 points) = ₹287.50 | ₹3,450 + one ₹2,000 milestone voucher = ₹5,450 | Renewal fee reversed (₹1.8 lakh is above ₹1 lakh) |
| Cashback SBI Card | 5% of ₹15,000 = ₹750 | ₹9,000 − ₹1,179 fee with GST = ₹7,821 | Renewal fee charged (₹1.8 lakh is below ₹2 lakh) |
From the second year, when SimplyCLICK’s renewal fee is reversed, Cashback comes out ahead by about ₹2,370 a year. In the first year, both cards charge their joining fee, so the gap is about ₹2,960. The voucher is counted at face value, so the gap is wider if you do not use it. SimplyCLICK still makes sense when your online spending is small, mostly with its partners, and you want the lower ₹499 fee. If you simply want the best SBI credit card for cashback, with no points to track, the Cashback SBI Card is the one to pick.
If you prefer points, the best SBI credit card for reward points on everyday spending is SimplySAVE or PRIME, thanks to their 10X categories, while ELITE and AURUM add milestone and premium point benefits. Points on cards like SimplyCLICK and SimplySAVE are worth 25 paise each (4 points = ₹1). Before you count them, check what your SBI reward points are worth and how to redeem them, since the ₹99 redemption fee and the 4,000-point rule affect the real value.
Best SBI Credit Cards for Flipkart and Amazon shoppers
If most of your shopping is on Flipkart and Myntra, the Flipkart SBI Card’s 5% and 7.5% beat the Cashback card on those two sites, but its renewal fee is waived only at ₹3.5 lakh. The Flipkart SBI Card’s cashback rates and caps are worth checking before you decide. Amazon is not a SimplyCLICK 10X partner, so for Amazon purchases, the Cashback SBI Card’s 5% on eligible online spends is usually the better SBI option, within its cap.
Best SBI Credit Cards for Travel and Shopping
If you want one card that rewards both everyday spending and trips, the best SBI credit card for travel and shopping is SBI Card ELITE for heavy spenders and SBI Card PRIME for moderate spenders. For people whose spending is mostly on flights and hotels, SBI Card MILES ELITE is the dedicated SBI travel credit card.
| Point | SBI Card ELITE | SBI Card MILES ELITE | SBI Card PRIME |
|---|---|---|---|
| Annual fee / reversed at | ₹4,999 / ₹10 lakh | ₹4,999 / ₹15 lakh | ₹2,999 / ₹3 lakh |
| Rewards | 2 points per ₹100; 5X on dining, department stores, and groceries | 6 Travel Credits per ₹200 on travel; 2 per ₹200 on other spends | 2 points per ₹100; 10 points per ₹100 on dining, department stores, movies, and groceries |
| Welcome benefit | ₹5,000 e-gift voucher | 5,000 Travel Credits | ₹3,000 e-gift voucher |
| Milestones | Bonus points at set annual spend levels, up to 50,000 points a year | 20,000 bonus Travel Credits at ₹12 lakh a year | Vouchers at quarterly and annual spend levels |
| Lounge visits | 8 domestic, 6 international | 8 domestic (plus 1 extra per ₹1 lakh spent, up to 15), 6 international | 8 domestic, 4 international |
| Forex markup | 1.99% | 1.99% | 3.5% |
| Other | Free movie tickets each year | Priority Pass membership; travel insurance coverage | Club ITC membership |
The MILES ELITE details match SBI Card’s own MILES card launch note. ELITE suits you if you will use its movie, milestone, and lounge benefits. MILES ELITE suits you if most of your eligible spending is travel and you value Travel Credits. PRIME suits you if you want lounge access at a lower fee and will cross ₹3 lakh a year; the PRIME card page lists its current vouchers and lounge terms. The ELITE card’s movie and milestone benefits and the PRIME card’s lounge and voucher benefits are reviewed in full separately.
Airline loyalists have two more options. The IndiGo SBI Card ELITE earns IndiGo BluChips. The Air India SBI Signature Card earns 10 points per ₹100 on Air India tickets (down from 30 points on 31 March 2025) and gives 8 domestic lounge visits, but its card page showed no Apply Now option when checked, so confirm that it is still open for applications.
Best SBI credit card for lounge access
For the best SBI credit card for lounge access, count the free visits you will actually use and any spend conditions attached to them.
| Card | Domestic Lounge Visits | International Lounge Visits | Condition |
|---|---|---|---|
| SBI Card ELITE | 8 a year (2 per quarter) | 6 a year (up to 2 per quarter), Priority Pass | None listed |
| SBI Card MILES ELITE | 8 a year, plus 1 extra per ₹1 lakh spent (up to 15 a year) | 6 a year | Pass membership |
| SBI Card PRIME | 8 a year | 4 a year (up to 2 per quarter) | None listed |
| Tata Neu Infinity SBI Card | 8 a year (2 per quarter) | 4 a year (1 per quarter) | Domestic visits need ₹75,000 spent in the previous quarter |
| Air India SBI Signature Card | 8 a year (2 per quarter) | Priority Pass membership; visits charged | Not applicable |
| BPCL SBI Card OCTANE | 4 a year (1 per quarter) | None | Not applicable |
| SBI Card PULSE | 4 a year (1 per quarter) | Priority Pass membership | Not applicable |
| PhonePe SBI Card SELECT BLACK | 4 a year (1 per quarter) | Priority Pass membership | Not applicable |
| Tata Neu Plus SBI Card | 4 a year (1 per quarter) | None | Needs ₹50,000 spend in the previous quarter |
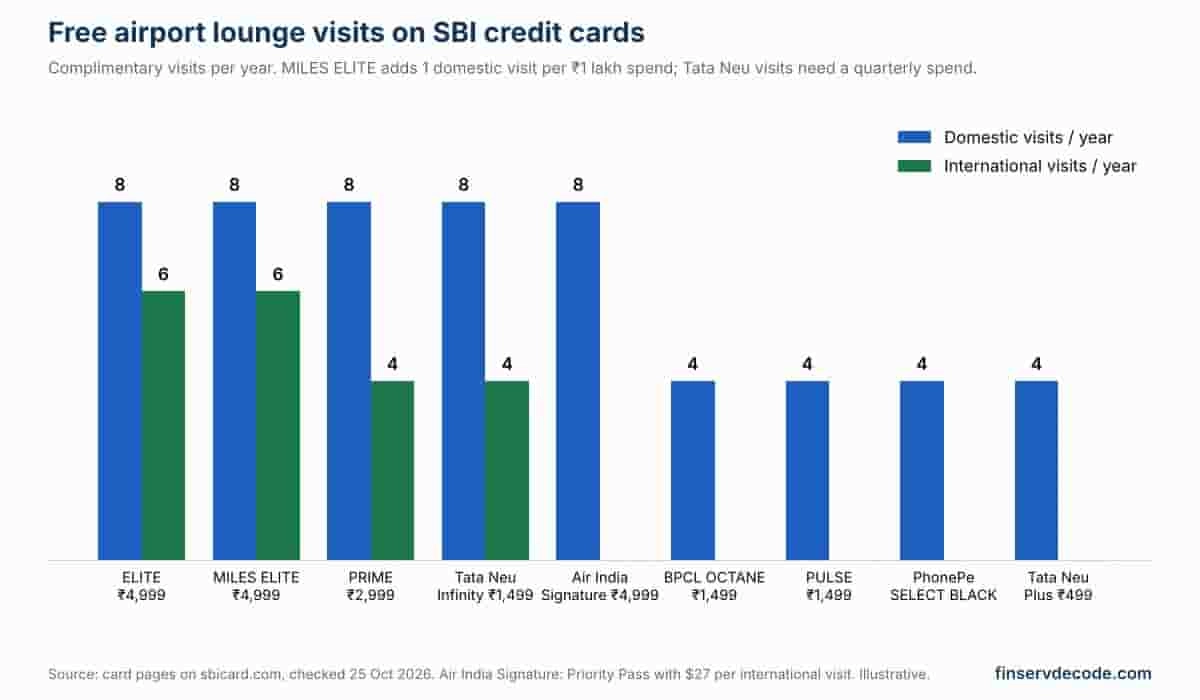
None of the cards compared here gives lounge access without an annual fee. The cheapest route is the ₹499 Tata Neu Plus, and only after ₹50,000 of spending in the previous quarter. International visits are through Priority Pass, and visits beyond the free count are charged.
Best SBI credit card for international transactions
For the best SBI credit card for international transactions, the foreign currency markup matters more than the reward rate. According to the MITC, ELITE, MILES ELITE, AURUM, and Tata Neu Infinity charge 1.99%, while most other SBI cards charge 3.5%. On ₹1 lakh of foreign spending, that is ₹1,990 against ₹3,500, before GST on the markup. If you travel abroad often or shop on international websites, a 1.99% card can save more than its rewards earn.
Best SBI Credit Card for Fuel
For the best SBI credit card for fuel, compare SBI’s two BPCL cards, but only if you fill up regularly at Bharat Petroleum pumps. Their value back is for BPCL fuel only, so they add little if you use other fuel brands.
| Point | BPCL SBI Card | BPCL SBI Card OCTANE |
|---|---|---|
| Annual fee / reversed at | ₹499 / ₹1 lakh | ₹1,499 / ₹2 lakh |
| Value back at BPCL | 4.25% (3.25% as points + 1% fuel surcharge waiver) | 7.25% (6.25% as points + 1% fuel surcharge waiver) |
| Points cap at BPCL | 1,300 points per billing cycle | 2,500 points per billing cycle |
| Other rewards | 5 points per ₹100 on dining, departmental stores, groceries, and movies | 10 points per ₹100 on dining, departmental stores, groceries, and movies (monthly cap applies) |
| Extras | Welcome bonus points | Welcome bonus points; 4 domestic lounge visits |
An illustrative example: Suppose you spend ₹5,000 a month on BPCL fuel, in two fills of ₹2,500 each (the value back applies to BPCL transactions up to ₹4,000 each). The BPCL SBI Card gives about ₹212 a month (₹162.50 in points plus ₹50 surcharge waiver), and OCTANE gives about ₹362 (₹312.50 plus ₹50), both within their point caps. Over a year, OCTANE gives about ₹1,800 more. Its fee is ₹1,000 higher (about ₹1,180 with GST) when neither fee is reversed, so OCTANE stays ahead by roughly ₹620 at this spend, before counting its lounge visits. Below this level of fuel spending, the cheaper BPCL SBI Card usually makes more sense. The BPCL SBI Card’s fuel rewards and the OCTANE card’s higher fuel value back are reviewed separately.
Best SBI RuPay Credit Card for UPI Payments
According to SBI Card’s UPI FAQ, only RuPay SBI credit cards can be linked to UPI apps; Visa, Mastercard, and Amex cards cannot. So the best SBI RuPay credit card is the one whose rewards include UPI spends. Among the cards compared here, the Tata Neu cards say so clearly:
| Card | Reward on UPI Spends (RuPay Variant) | Annual Fee / Reversed At |
|---|---|---|
| Tata Neu Infinity SBI Card | 1.5% as NeuCoins | ₹1,499 / ₹3 lakh |
| Tata Neu Plus SBI Card | 1% as NeuCoins | ₹499 / ₹1 lakh |
Tata Neu Plus is the lower-fee pick for the best SBI credit card for UPI payments, while Infinity gives a higher NeuCoins rate, lounge access, and a 1.99% forex markup at a higher fee. Before you link a RuPay SBI card to UPI, know these rules from SBI Card’s FAQ:
- Only merchant payments are allowed. You cannot send money to friends or family (P2P).
- Limits are ₹5 lakh per transaction and ₹10 lakh a day (₹1 lakh at small offline merchants), within your credit limit.
- There is no fee for linking the card or paying with it, and UPI spends earn rewards as per the card’s terms, except excluded categories.
- Choose the RuPay variant when applying. Many SBI cards are offered on more than one network.
- PhonePe SBI Card SELECT BLACK gives no points on UPI payments made through apps other than PhonePe from 1 July 2026, according to its revised terms, which also add monthly caps on points.
Zero Annual Fee or Lifetime Free SBI Card?
None of the 16 cards compared here are lifetime free. The fee-free options are either time-limited or depend on how much you spend. The closest options for the best SBI credit card with zero annual fee are:
| Card | How the Fee Goes to Zero | Note |
|---|---|---|
| SBI Card Unnati | No annual fee for the first 4 years; ₹499 from year 5 | Issued only against a fixed deposit with SBI |
| SimplyCLICK, SimplySAVE, BPCL SBI Card, Tata Neu Plus | ₹499 renewal fee reversed when yearly spends reach ₹1 lakh | The first-year fee is still paid |
| Cashback SBI Card | ₹999 renewal fee reversed at ₹2 lakh of yearly spends | Cashback is capped, and many categories are excluded |
A spend-based reversal is not the same as a lifetime-free card. You pay the first-year fee, and the renewal fee is reversed only in the years you cross the spend. So the practical answer to the best SBI credit card lifetime free question is a ₹499 card that you use for at least ₹1 lakh a year, which is about ₹8,350 a month.
SBI Credit Card for Beginners, Students and Salaried People
SBI Card lists eligibility on each card’s page, and approval depends on your income, credit history, and SBI Card’s checks. Within that, these are the usual starting points:
| Profile | Best SBI Card | Why |
|---|---|---|
| Student or no credit history | SBI Card Unnati | Secured against a fixed deposit; no fee for 4 years; still subject to approval |
| First card, salaried, mostly online spending | SimplyCLICK SBI Card | ₹499 fee, ₹1 lakh reversal, online rewards |
| First card, salaried, mostly offline spending | SimplySAVE SBI Card | ₹499 fee, 10X on everyday categories |
| Household spending on groceries, bills, and shopping | SimplySAVE or Cashback SBI Card | Pick Cashback if most spending is online and outside excluded categories |
| Salaried, ₹25,000 or more in monthly card spends | SBI Card PRIME or Cashback SBI Card | ₹25,000 a month is ₹3 lakh a year, PRIME’s reversal level, if those spends count |
| Salaried, wants simple rewards | Cashback SBI Card | No points to track; cashback is credited to the statement |
So the best SBI credit cards for salaried employees depend on spending patterns more than income. The best SBI credit card for beginners is usually SimplyCLICK or SimplySAVE, because the fee is low and easy to reverse. For students, the best SBI credit card for students is usually Unnati against a fixed deposit, because unsecured cards generally need income proof and a credit history.
Best Premium SBI Credit Card: AURUM vs ELITE vs MILES ELITE
For the best premium SBI credit card, AURUM is SBI Card’s top tier, while ELITE and MILES ELITE are the premium cards most people can apply for directly.
| Point | AURUM | SBI Card ELITE | SBI Card MILES ELITE |
|---|---|---|---|
| Annual fee / reversed at | ₹9,999 / ₹12 lakh | ₹4,999 / ₹10 lakh | ₹4,999 / ₹15 lakh |
| Base reward | 4 points per ₹100 | 2 points per ₹100 | 2 Travel Credits per ₹200 |
| Forex markup | 1.99% | 1.99% | 1.99% |
| Redemption | On AURUM’s own portal only; no cash or statement credit | Statement credit, vouchers | Air miles, hotel points, travel |
AURUM’s points can be used only on its own portal, according to the AURUM reward portal terms, so don’t compare them with cashback at face value. ELITE costs about half as much and lists fixed movie, milestone, and lounge benefits, so its value is easier to work out.
SBI Card Compare: Head-to-Head Matchups
Use these matchups to compare SBI cards that people often shortlist together.
SBI ELITE vs PRIME
In SBI ELITE vs PRIME, ELITE costs ₹2,000 more a year and needs ₹10 lakh in spends to reverse the fee, against PRIME’s ₹3 lakh. ELITE adds 2 more international lounge visits, free movie tickets, bigger milestone bonuses, and a 1.99% forex markup. PRIME suits you if you want lounge access at a lower fee and will cross ₹3 lakh a year. ELITE pays back its higher fee only if you use the movie benefit, the milestone points (up to 50,000 a year, worth ₹12,500 at 25 paise a point), and the international visits.
SBI SimplyCLICK vs SimplySAVE
Both cost ₹499 with a ₹1 lakh reversal. In SBI SimplyCLICK vs SimplySAVE, the difference is where you spend. SimplyCLICK rewards online partners (10X) and other online spends (5X). SimplySAVE rewards dining, movies, groceries, and departmental stores (10 points per ₹150) online or offline. Pick the one that matches the bigger share of your monthly bills. The SimplySAVE card’s everyday rewards are reviewed separately.
SBI Cashback vs SimplyCLICK
In SBI Cashback vs SimplyCLICK, Cashback pays 5% on eligible online spends, against SimplyCLICK’s 2.5% at partners and 1.25% elsewhere online. But Cashback costs ₹999 and caps online cashback at ₹2,000 per statement. The worked example above shows the gap at ₹15,000 a month; run the same sum with your own spending split.
SBI SimplySAVE vs BPCL SBI Card
Both cost ₹499 with a ₹1 lakh reversal. In SBI SimplySAVE vs BPCL, SimplySAVE gives more on dining and groceries (10 points per ₹150, against BPCL’s 5 points per ₹100), while the BPCL card gives 4.25% on fuel at BPCL pumps. If fuel at BPCL is a large share of your spending, pick the BPCL card; for dining, groceries and movies, SimplySAVE fits better.
SBI SimplyCLICK vs PULSE
These suit different people. SimplyCLICK (₹499) is an online shopping card. PULSE (₹1,499) is a health and fitness card, with a smartwatch as its welcome gift, fitness and pharmacy memberships, and 10 points per ₹100 on pharmacy, sports, dining and movies. Count the welcome gift at its value to you, not its listed price.
Costs to Check Before You Apply
A card’s rewards are only half the picture. These costs can wipe them out:
- Interest: The MITC lists finance charges of up to 3.75% a month (45% a year) on unsecured SBI cards.
- Paying only part of your bill costs far more than any reward you earn, so pay the full amount by the due date.
- Foreign currency markup: 3.5% on most cards, and 1.99% on ELITE, MILES ELITE, AURUM and Tata Neu Infinity.
- Renewal fee: charged every year you do not reach the reversal spend, plus 18% GST.
- Reward redemption fee: SBI Card charges ₹99 plus tax per batch when you redeem points for statement credit or products.
How each of these fees is worked out is covered in the guide to credit card charges.
How to Choose and Apply for the Right SBI Card
- Add up last year’s spending by category: online shopping, groceries, fuel, travel, bills. The biggest category usually decides the card.
- Check whether you will cross the fee-reversal spend. If not, count the full fee plus 18% GST every year.
- Read the exclusions for that specific card. Fuel, rent, utilities, wallets, and government payments are treated differently across cards. For example, Cashback excludes fuel, while the BPCL cards reward BPCL fuel.
- Check the card’s page, Key Fact Statement, and MITC on sbicard.com for the latest terms, because caps and partners change through notices.
- Apply on sbicard.com or the SBI Card app. The full process, documents, and approval time are covered in how to apply for an SBI credit card online.
Brand offers and sale discounts on SBI cards change every few weeks, so this guide compares only each card’s standing benefits, fees, and reversals.
Frequently Asked Questions
Which is the best SBI credit card?
There is no single answer to which is the best SBI credit card. For eligible online shopping, it is the Cashback SBI Card; for a low fee, SimplyCLICK or SimplySAVE; for BPCL fuel, BPCL SBI Card OCTANE; for travel and lounges, ELITE or MILES ELITE; and for UPI, the Tata Neu cards on RuPay.
Which SBI credit card is best for online shopping?
The Cashback SBI Card, for most online shoppers. It pays 5% on eligible online spends on any website, with online cashback capped at ₹2,000 per statement. The Flipkart SBI Card is better if you shop mostly on Flipkart and Myntra.
Which SBI credit card has no annual fee?
SBI Card Unnati has no annual fee for the first 4 years (₹499 from year 5) and is issued against a fixed deposit. Other cards charge a fee but reverse the renewal fee when yearly spends cross a set amount, such as ₹1 lakh for SimplyCLICK and SimplySAVE.
Is any SBI credit card lifetime free?
None of the cards compared here is lifetime free. A ₹499 card used for ₹1 lakh or more a year has its renewal fee reversed, but that is a spend-based reversal, not a lifetime-free card.
Which SBI credit card is best for lounge access?
SBI Card ELITE and MILES ELITE give 8 domestic and 6 international visits a year. SBI Card PRIME gives 8 domestic and 4 international visits at a lower fee.
Which SBI credit card can be used on UPI?
Only RuPay SBI credit cards. The Tata Neu Plus and Infinity cards give NeuCoins on UPI spends on their RuPay variant. UPI on a credit card works only for payments to merchants.
Which is better, SBI ELITE or PRIME?
PRIME, if you want lounge access at a lower fee and will spend ₹3 lakh a year. ELITE, if you will use its movie benefit, milestone points, and 6 international visits enough to cover its ₹2,000 higher fee.
What is the Cashback SBI Card cashback limit?
From 1 April 2026, it is ₹2,000 on eligible online spends and ₹2,000 on eligible offline spends per statement cycle, or ₹4,000 in total. Excluded categories earn no cashback.
Which SBI card is best for fuel?
BPCL SBI Card OCTANE gives 7.25% value back at BPCL pumps, and the cheaper BPCL SBI Card gives 4.25% on transactions up to ₹4,000 each. Both work only at BPCL pumps.
Which SBI card is best for Amazon shopping?
Amazon is not a SimplyCLICK 10X partner. The Cashback SBI Card’s 5% on online spends applies to eligible Amazon purchases, within its cap and exclusions.
Can I hold more than one SBI credit card?
Yes, subject to SBI Card’s credit assessment. Many people pair an online card such as Cashback with a category card such as BPCL or SimplySAVE.
Conclusion
The best SBI credit cards for you depends on where your money goes and how much you spend in a year, not on which card has the longest benefits list. For most online shoppers, the Cashback SBI Card gives the most value, as long as you stay within its ₹2,000 monthly online cap and avoid its excluded categories. If you want a low fee, SimplyCLICK suits online spenders and SimplySAVE suits dining and grocery spenders, and both reverse the ₹499 fee at ₹1 lakh a year. BPCL SBI Card OCTANE makes sense only if you fill up regularly at BPCL pumps, while ELITE, MILES ELITE and PRIME are worth their higher fees only if you will actually use the lounge visits, milestones and lower forex markup.
Before you apply, compare the annual fee plus GST with the yearly spend needed to reverse it, and count only the rewards and benefits you will really use. If a card comes out ahead only when you count every voucher and lounge visit, the cheaper card is usually the better choice. SBI Card revised caps, partners, and fee reversals on several cards in 2025 and 2026, so check the latest terms on the card’s page at sbicard.com before you apply.
Disclaimer
This article is for general information only and is not financial advice or a recommendation to apply for any card. Finserv Decode is not connected with SBI Cards and Payment Services Limited and earns no commission from this page. Fees, fee reversals, foreign currency markup and interest rates are taken from SBI Card’s MITC dated 21 August 2026; rewards, caps, lounge access and other features are taken from SBI Card’s card pages and notices, as checked as of now, and can change without notice. Worked examples are illustrative, assume eligible spends, and value reward points at ₹0.25 where the card lists 4 points = ₹1. They do not guarantee any return or card approval. Charts in this article are illustrative and are not official SBI Card documents. Please confirm the latest terms on sbicard.com before applying.